Blog

  • Can I Sell My House Before Foreclosure?

    Can I Sell My House Before Foreclosure?

    If you are behind on your mortgage or have received a foreclosure notice, you may still have options.

    In many cases, a homeowner can sell the property before foreclosure is completed. The sooner you understand your timeline, your mortgage payoff, and your home’s value, the more choices you may have.

    Can I still sell my house?

    Often, yes. If you still own the property and the foreclosure sale has not taken place, selling may still be possible. If the home is worth more than what you owe, a sale may allow you to:

    • Pay off the mortgage
    • Cover closing costs and other liens
    • Keep any remaining equity

    The key is understanding the numbers before time runs short.

    Do I have enough time?

    That depends on where you are in the foreclosure process. If you already have a scheduled foreclosure date, timing becomes especially important. Waiting until the last minute can reduce your options. Start by finding out:

    • How much you owe
    • Whether a foreclosure sale has been scheduled
    • What your property is worth
    • How quickly a sale could realistically close

    Will I get any money from the sale?

    Possibly. If your home sells for more than the mortgage payoff, liens, and selling expenses, you may be able to keep the remaining proceeds. That is why it is important to look at your estimated net proceeds, not just the sale price.

    What are my options besides foreclosure?

    Selling may be one option, but it is not always the only one. Depending on your situation and loan, your mortgage servicer may offer options such as:

    • Loan modification
    • Repayment plan
    • Forbearance
    • Short sale
    • Deed-in-lieu of foreclosure
    •  

    If your goal is to stay in your home, contact your mortgage servicer as soon as possible and ask about available loss-mitigation options.

    Be careful who you trust

    Homeowners facing foreclosure can become targets for scams. Be cautious of anyone who:

    • Guarantees they can stop foreclosure
    • Tells you to stop talking to your mortgage company
    • Asks you to send mortgage payments to them
    • Pressures you to sign documents you do not understand
    • Demands large upfront fees

    Always understand exactly what you are agreeing to.

    Start With the Facts

    If you are considering selling before foreclosure, begin by gathering:

    • Your latest mortgage statement
    • Your estimated payoff amount
    • Your foreclosure timeline
    • Your property’s approximate value

    Then compare your available options. At H&M Property Partners, we can help you understand what a potential property sale might look like, including the timing, estimated payoff, and possible equity. There is no pressure and no obligation.

    If you are asking:

    Can I still sell?
    How much time do I have?
    What happens to my equity?
    What would an offer look like?

    We are happy to walk through the numbers with you.

    This article is for general educational purposes and is not legal, tax, credit, or financial advice. Foreclosure laws and timelines vary by state and individual circumstances.
  • Selling to Avoid Foreclosure: Questions Homeowners Ask Us Most

    Most people don’t grow up thinking about how to sell a house under pressure. If you’re weighing this decision, here are the questions that come up most often, answered plainly.

    Will I actually get anything out of the sale, or does the lender take it all? If there’s equity in the home, meaning it’s worth more than what’s owed, that equity is yours at closing, not the lender’s. The lender is paid off from the proceeds, and whatever’s left over comes to you. That’s one of the biggest differences between selling on your terms and letting a foreclosure run its course, where equity is often lost.

    Will my credit still take a hit if I sell instead? A history of late payments will still show up, but a completed foreclosure is a separate, more serious mark that tends to stay on a credit report longer and does more damage. Selling before that point avoids that specific outcome.

    Can I stay in the house until I find somewhere else to go? Often, yes, within reason. Closing dates are negotiable, and many sellers arrange a short window after closing to handle moving logistics. Worth raising directly with whoever you’re working with rather than assuming either way.

    Do I need to fix anything before selling? Not when you’re selling directly to us. The property sells in its current condition, no repairs, no cleaning, no staging required, which matters when money and time are already tight.

    Is selling my only option? No. Reinstatement, forbearance, and loan modification are all worth exploring if the underlying financial issue is something that can genuinely be resolved. Selling tends to make the most sense when those paths aren’t realistic in the time available, or when keeping the house isn’t the goal anymore. Our foreclosure guide covers those other paths in more detail if you want the fuller picture.

    If you’ve got a question we haven’t covered here, that’s normal, every situation is different. Reach out us here and we’ll talk through yours specifically.

  • How Much Do Cash Home Buyers Actually Pay?

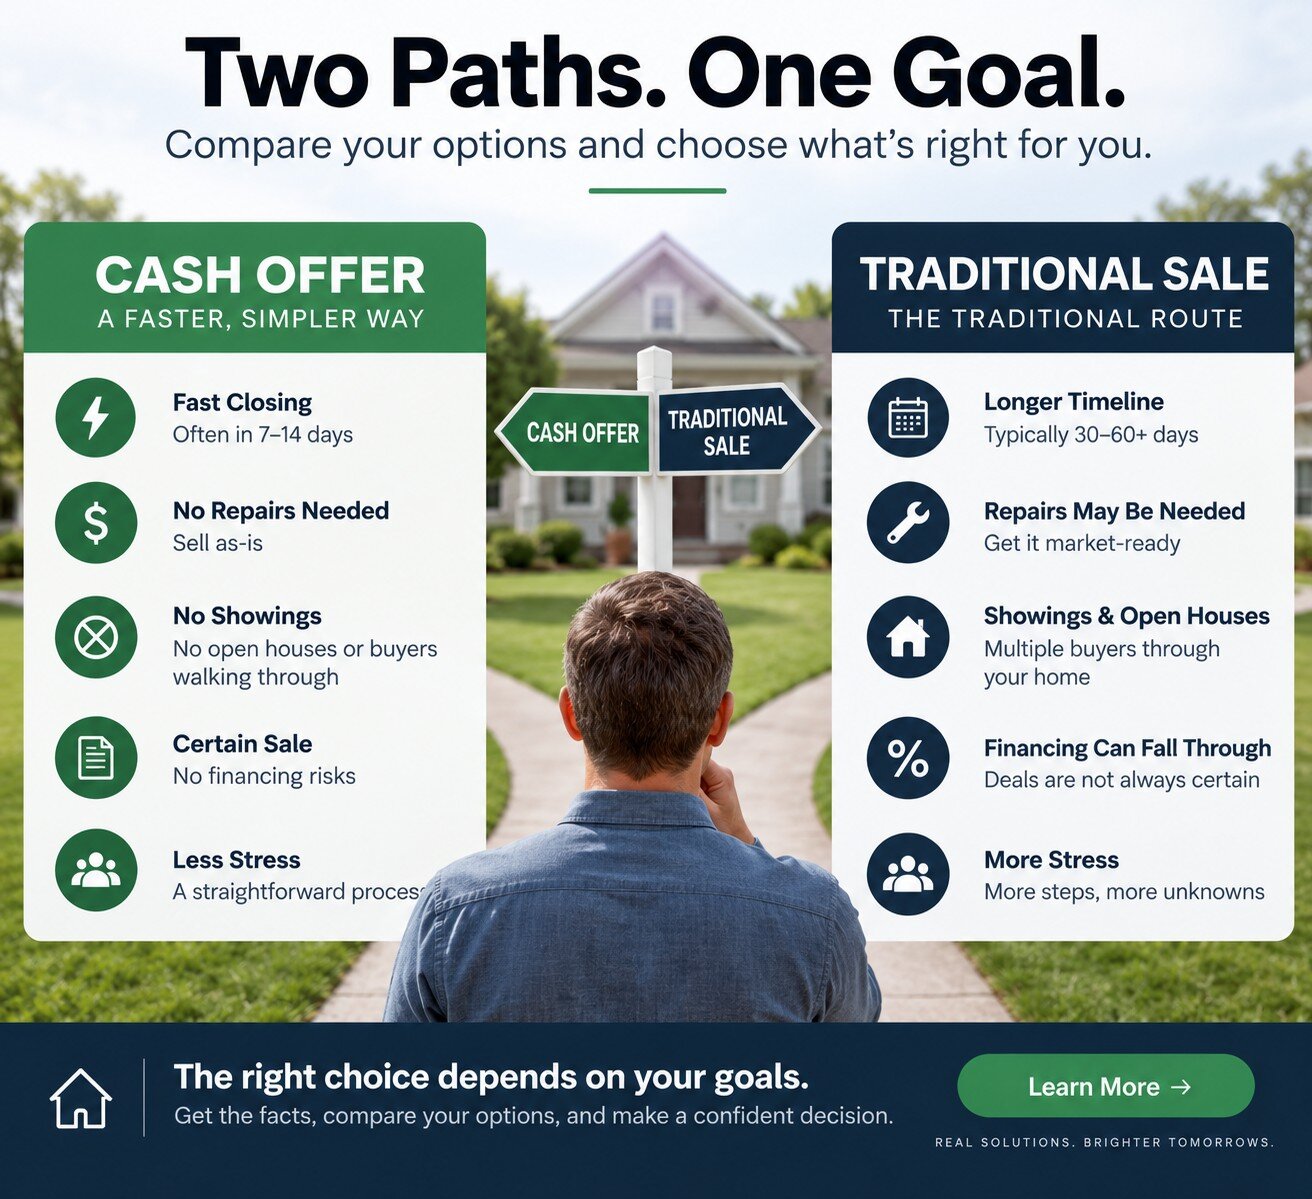
    Compare a cash offer to a traditional home sale,

    It is a fair question, and one worth answering honestly rather than with a vague range. A cash offer is not the same number you would see on a listing and understanding why helps you compare it accurately to your other options.

    A listing price reflects what a house might sell for on the open market, after repairs, after staging, after months of showings, and after a buyer’s financing clears. A cash offer reflects the property as it sits today, with none of that in between. The gap between the two numbers usually covers the cost of repairs the buyer will make, the carrying costs and time involved in reselling the property, and the certainty of a closing that does not depend on a lender’s approval.

    The right way to think about it is not listing price versus cash offer in isolation, it is net proceeds versus net proceeds. A traditional sale often nets more on paper, but only after subtracting realtor commissions, repair costs, staging, and months of mortgage payments or vacancy while it sits on the market. A cash offer nets less on paper but comes with none of those subtractions and a much shorter timeline.

    Which one actually puts more in your pocket depends on the specific property, its condition, and how much time you have. That is a calculation worth running on your actual numbers rather than a rule of thumb.

    If you want an honest, no-obligation number for your specific house, request a cash offer and we will walk you through exactly how we arrived at it.

  • Selling Fast to Stop a Foreclosure: What’s Actually Realistic

    If a sale date is already set, the question isn’t really whether to sell, it’s whether there’s enough time left to do it. Here’s an honest look at what that timeline involves.

    A traditional home sale, listing, showings, negotiating, waiting on a buyer’s financing, appraisal, inspection, closing, usually takes a couple of months from listing to close, sometimes longer if the buyer’s loan runs into a snag. If your remaining time is shorter than that, a traditional listing on its own often isn’t fast enough.

    Selling directly to a buyer removes most of what makes a traditional sale slow. There’s no buyer financing to wait on, because the purchase isn’t contingent on a mortgage approval. There’s no repair negotiation, because the house sells in its current condition, no work required on your end. There’s no staging or showings eating into the time you have left. What’s left is mostly paperwork and a closing date, which can often move quickly once terms are agreed on.

    That speed matters most in one specific situation: your timeline is tight, reinstatement or a loan modification isn’t realistic in the time available, and you need the process resolved before it costs you your equity and your credit. For the fuller picture on how the Virginia foreclosure process works and what your specific dates might look like, our foreclosure guide covers that in more depth, and we’d rather talk through your exact dates directly than guess at general numbers here.

    We’re local and we work around your schedule, not ours. Tell us where things stand and we’ll give you a straight answer about what’s realistic, no runaround.

  • Why Some Luxury Sellers Choose Financing Over an All-Cash Exit

    Cash is still the dominant story in the luxury market. Most high-end transactions close all-cash or with conservative leverage, and that is not changing anytime soon. But a smaller, specific group of sellers are choosing a different path: carrying financing on the sale themselves instead of taking a lump sum at closing.

    It tends to show up in a few recurring situations. A seller sitting on a large, long-held gain who does not want the entire tax impact landing in a single year. A seller who does not need full liquidity right away and would rather receive steady income on favorable terms than have the proceeds sit in cash. A seller who values discretion and prefers a private, negotiated sale over a public listing and a bidding process. And occasionally, a property that has sat longer than expected, where financing widens the pool of qualified buyers beyond those who can write a check for the full price today.

    None of this makes financing the right call for every luxury seller, most will still prefer a clean, all-cash exit. But for the sellers where it fits, it is worth understanding as a real option rather than something reserved for distressed sales. It is a structural choice, not a sign of trouble.

    For agents working with a seller who might be a fit for this conversation, or who wants to understand the mechanics before bringing it up, that is exactly what we are here for. Reach out to us HERE and we let’s get the conversation started.

  • Selling an Inherited House in Chesterfield County: What You Need to Know

    Inheriting a house in Chesterfield County often comes with more questions than answers. Maybe the property sat empty for months before you found out about it. Maybe it needs work you did not expect, or the estate is still working through probate and you are not sure what you are even allowed to do yet.

    The first thing worth knowing: you usually do not have to wait for probate to fully close before exploring your options. Depending on how the estate is structured, an executor or personal representative can often move forward with a sale earlier than people assume. Every estate is different, so this is worth confirming with the attorney handling the estate rather than guessing.

    The second thing worth knowing: condition rarely disqualifies a property from being sold. Older homes in neighborhoods like Midlothian, Chester, and Bon Air often carry deferred maintenance, especially if a parent or relative lived there for decades. A traditional listing usually means repairs, staging, and months of showings before a sale closes. Selling directly to a buyer skips that entirely, the property sells in its current condition.

    The third thing worth knowing: you are not required to decide alone or right away. If there are multiple heirs, everyone’s input matters, and taking time to get on the same page is worth more than rushing to a decision under pressure.

    For more on what selling directly looks like in Chesterfield County specifically, see our Chesterfield County page. If you would rather just talk through your specific situation, that is usually faster than trying to sort it out from general information online, you can also connect with us HERE.

  • Selling Your House to Avoid Foreclosure: Weighing Your Options

    If you’ve fallen behind on your mortgage, the instinct is often to fight to keep the house no matter what. Sometimes that’s the right call. Other times, selling is the option that actually solves the problem instead of just delaying it. Here’s how the paths compare, without any of the pressure.

    Reinstatement and loan modification both let you stay in the house, but they only work if whatever caused the shortfall, lost income, a medical bill, a rate change, is genuinely resolved. If it isn’t, you can end up back in the same spot a few months later, further behind and with less room to react.

    Selling does something reinstatement and modification can’t: it lets you walk away with whatever equity has built up in the home instead of risking it. For a full walkthrough of what actually happens during a Virginia foreclosure and what your timeline realistically looks like, see our guide on stopping foreclosure. Every situation moves at a different pace, so it’s worth talking through your specific dates directly rather than relying on general timelines you find online.

    A traditional listing can work well if you have enough runway before things move further along, and it usually captures the most value if your house doesn’t need repairs and you have time to wait for the right buyer. If your situation is tighter than that, or the property needs work you’d rather not put money into first, selling directly to a buyer like H&M Property Partners means no repairs, no showings, and no waiting on someone else’s financing to fall through.

    There’s no single right answer here. If you can genuinely get current and stay there, reinstatement may be the better move. If the numbers don’t work out long term, selling on your own terms, before the situation forces the issue, usually leaves you in a stronger position than waiting to see what happens.

    You have more options than you might think. If you want to talk through what selling would actually look like for your house, request an offer and we’ll walk through it together, no pressure in either direction you choose.